





For those living, investing, or managing global assets in the United States long-term, Capital Gains Tax is an inescapable topic for almost every immigrant family.
Many clients discover only when selling stocks, funds, properties, or undergoing family asset restructuring that: "It’s not just about how much you earned, but how much you have to pay in taxes."
1. What is Capital Gains Tax?
Capital gain is defined as: Sale Price - Original Cost = Capital Gain.
Common assets involved include:
• Stocks, funds, and bonds
• Investment properties
• Corporate equity
• Certain long-term financial assets
In the U.S., the fundamental distinction for Capital Gains Tax is whether the asset was held for more than one year; only assets held for over a year qualify for preferential long-term capital gains tax rates. However, the final tax rate still depends on personal income level, potential surtaxes, and state tax factors.
2. Short-Term Capital Gains:
The higher-tax category
What are short-term capital gains?
• Gains from the sale of assets held for less than one year
• Examples: Day trading stocks, short-term asset flipping
Tax rules:
Short-term capital gains do not enjoy any preferential rates; they are taxed as ordinary income at personal income tax rates.
The current federal ordinary income tax brackets range from 10% to 37%.
In other words, if you are a high-income earner, short-term investment gains may be taxed at a rate as high as 37%.
3. Long-Term Capital Gains:
The most important "tax incentive zone" in the U.S.
What are long-term capital gains?
• Gains from the sale of assets held for more than one year
• This is a core policy designed to encourage long-term investment and retention of assets in the U.S.
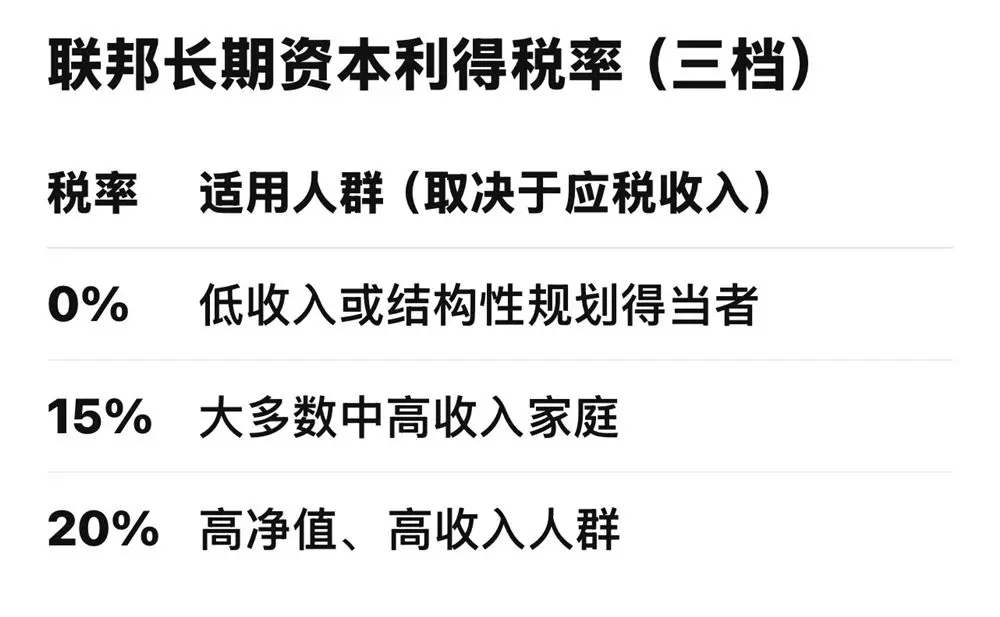
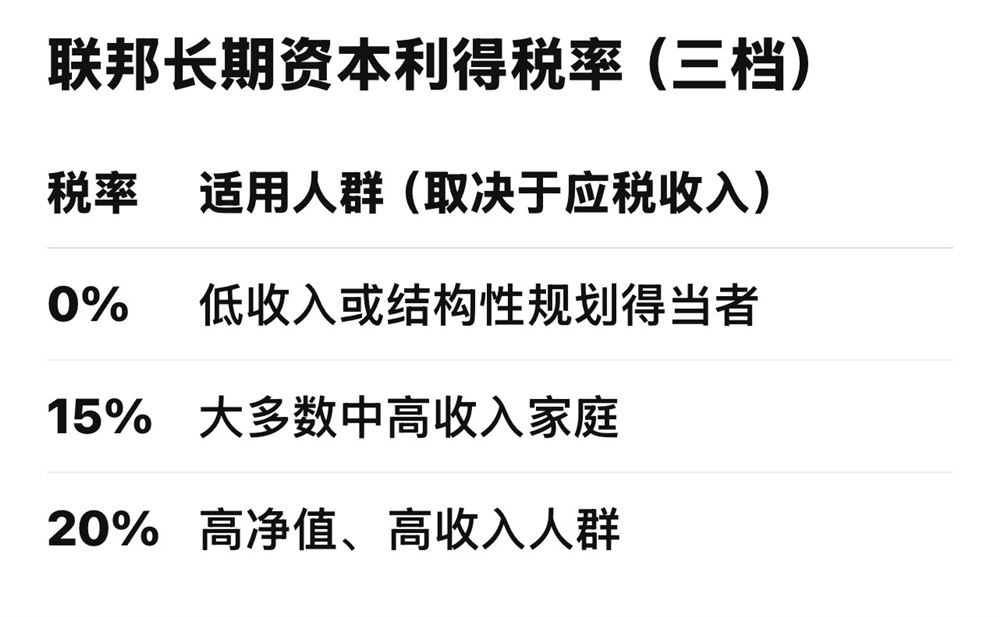
For many immigrant families, waiting to cross the "one-year" threshold before selling an asset can potentially drop the tax rate from 37% down to 15% or 20%.
4. Note to high-income individuals:
The 3.8% "invisible tax"
In addition to the aforementioned rates, there is an often-overlooked but significant surtax in the U.S.:
Net Investment Income Tax (NIIT)
• Rate: 3.8%
• Applies to:
• High-income individuals / families
• Net investment income (including capital gains)
This means for some high-net-worth families, the "effective federal tax burden" on long-term capital gains may be: 20% + 3.8% = 23.8%.
5. Not all assets
qualify for the "15% / 20%" rate
Please note: Collectibles (art, antiques, certain precious metals) or other special assets may be subject to a federal capital gains tax rate of up to 28%.
Different asset types follow different tax logic; they cannot be treated uniformly.
6. Why should "immigrant families"
pay closer attention to Capital Gains Tax?
For long-term clients of WorldWay, common scenarios include:
• Selling properties in the U.S. or overseas
• Adjusting stock/fund portfolios
• Transferring family assets from individual ownership to trusts or corporations
• Long-term asset layout planning for children and the next generation
Capital Gains Tax is not merely a "calculation problem"; it is a systematic planning issue involving timing, immigration status, asset structure, law, and taxation.
7. An important reminder
When selling the same property or the same block of stock:
Some people pay 15%,
Some people pay 23.8%,
Others, through structural design, can legally defer or optimize their tax burden.
The difference often lies in whether one has planned in advance.
If you are currently or soon to be involved in:
• Long-term family planning
• Coordinated design of immigration status and tax residency
You may wish to learn more about the relevant tax and legal rules based on your own situation. If necessary, please contact WorldWay Group, and we will collaborate with our local professional teams in the U.S. to provide you with sound, long-term comprehensive planning advice.
For inquiries in mainland China: 400-138-2929; Hong Kong customer service center: (852) 2802 8798
Disclaimer: 1. This article provides general information only and does not constitute any tax, legal, or investment advice. 2. U.S. tax law is complex and may vary depending on personal income level, asset type, filing status, and annual policy changes. 3. Before making any specific decisions, please consult with a professional tax accountant, lawyer, or compliance consultant.